Have your kids told you about their plan of saving for a new toy, then spend half their pocket money on snacks a few days later?
If this sounds familiar, telling them to save more carefully probably won’t help much. They may understand what saving means, but they’re still learning how to stick to a plan when something else catches their eye.
A money saving plan for kids gives them something specific to work towards. They know how much they need, how much they can put aside, and roughly how long it will take. Games can make these decisions easier to practise, especially before children start managing larger amounts of money.
Saving is one part of a wider financial education. If you’re introducing money concepts to your child for the first time, read our complete parent guide to financial literacy for kids.
You can try with a few coins, a sheet of paper and a goal your child really cares about are enough to get started.
How can you teach kids to save money through games?
Children can learn how to save money by practicing three things: setting a goal, deciding how much to put aside, and resisting the urge to spend before they reach it. A game gives them room to try these decisions without worrying about making a costly mistake.
Start with a goal they understand. Maybe a new toy, a console game, a book or other things. Find out how much it costs, then help your child figure out what they would need to do to afford it.
Keep the first activity manageable. If the goal feels too far away, break it into smaller milestones. A child saving $24, for example, could track progress at $6, $12, $18 and $24. They get to see that their contributions are adding up, even if they can’t buy the item yet.
It also helps to separate saving from spending. Children don’t need to put away every dollar they receive. They need to learn how to make room for a future goal while deciding what they can afford to spend now.
Then, you can use different games to practise the harder parts of saving, such as waiting before buying something or changing a plan when an unexpected cost comes up.
Play can give children a low-pressure way to practise these decisions. Read more about why kids learn better through play and how activities can support their learning.
5 saving games and challenges to help kids build better habits
An easy starting point is using a savings jar. But, children also need practice making decisions. Below are five activities that cover different parts of the process, from working out a target to deciding what to do when a plan goes sideways. Most can be done at home easily with paper and play money.
1. The savings jar challenge
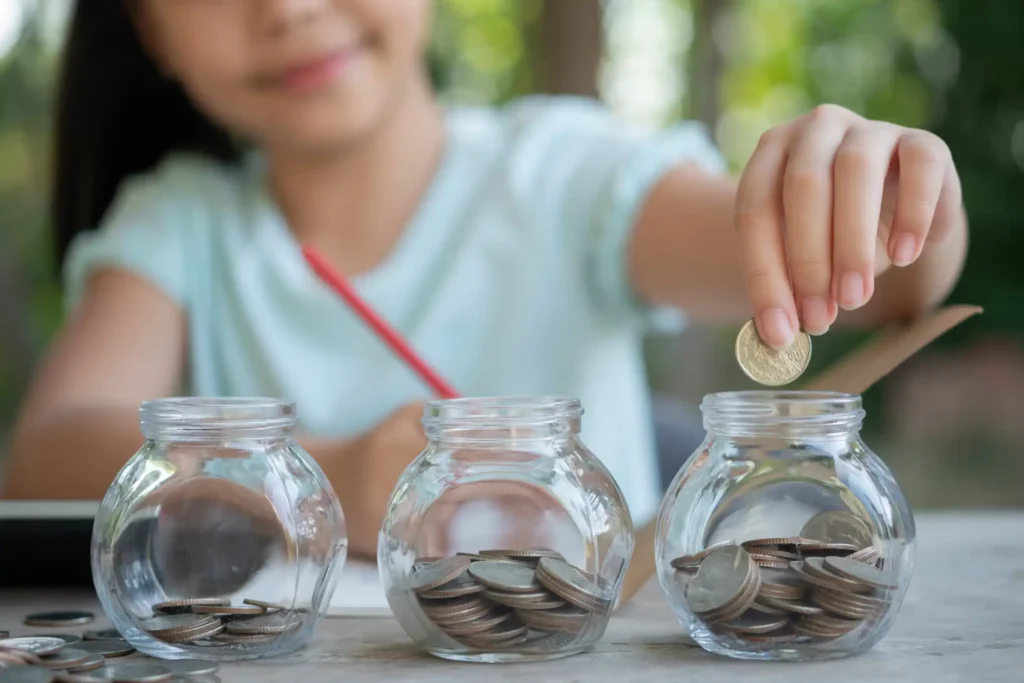
Give your child a jar or container and a goal to save towards. Write the target amount on a piece of paper and put it beside the jar (or stick it on the jar). If they want a toy that costs $24, mark four milestones on the tracker, each worth $6.
Every time your child adds money, let them update the tracker. You could use stickers, colour in a bar or draw a small picture to represent each milestone. The point is to make their progress visible, rather than leaving them to guess how much they have saved.
If your child receives pocket money regularly, you can also set up two containers: one for saving and one for spending. Agree on how much goes into each when the money arrives. That way, your child has some money available to enjoy now without losing track of the longer-term goal.
2. The backwards savings planner
For this game, give your child a goal, its price and a deadline. Ask them to work backwards to figure out how much they need to save each week.
Say a board game costs $30 and your child wants to buy it in six weeks. They would need to save $5 a week to reach the target, assuming they start from $0 and make the same contribution each week.
Now change the situation. What if the game costs $36? What if they want to buy it in four weeks? Recalculate the amount together and explain what has changed.
It will be more useful if you can discuss whether the plan is realistic. If your child only receives $4 in pocket money each week, saving $5 weekly won’t work unless they have another suitable source of money. They could choose a cheaper item or give themselves more time.
3. The 24-hour wish list
Your child sees something they want at the shop. They ask for it, you say no, and the conversation becomes a familiar back-and-forth. A wish list gives both of you another way to handle this.
When your child wants to buy a non-essential item, write down its name, price and the date. Agree to revisit the list 24 hours later. If the item is still on their mind, they can consider whether it’s worth saving for.
Sometimes they’ll still want it. That’s fine. Other times, they may decide they’d rather keep their money for something else. Either way, they’ve had time to think before spending.
For younger children, draw the item or use a picture and mark the day you’ll review it. Older children can keep a written list and compare a few things they want.
Try not to use the waiting period to talk them out of every purchase. The point isn’t to make children feel that spending is wrong. It’s to help them notice the difference between wanting something right now and deciding that it’s worth the money.
You can build on this activity by helping your child understand the difference between wants and needs especially when they’re deciding what is worth spending money on.
4. The surprise-expense game
A savings plan can look easy until something else comes up. Children can practise responding to changes through a pretend budget game.
Give your child $20 in play money. Tell them they want to save $15 towards a toy, then introduce a scenario card. It might say that a birthday gift for a friend will cost $3, or that the toy now costs more than expected.
Ask your child what they want to do. They might postpone the toy, reduce another planned purchase or extend the time they need to save. Let them explain their choice before you discuss the options together.
You can make the scenarios more relevant to your family as your child gets used to the game. Keep the situations realistic for their age, and avoid using essentials such as food or school needs as things they must sacrifice to reach a savings target.
They might make a different choice from you, and that gives you something useful to talk about. What matters is whether they understand how their decision affects the money they have left and the goal they’re working towards.
5. The spending trade-off game
Give your child $10 in pretend money and a menu of items they can buy. A snack costs $2, a small toy costs $5 and a book costs $6. Their task is to choose what they want while keeping at least $4 aside for a savings goal.
Let them make their choices and calculate what remains. If they spend too much to meet the saving target, ask them to look at the menu again. Is there something they’d rather skip? Could they choose a less expensive item? Or would they prefer to keep the purchases and change their savings plan?
Run another round with different prices or items. Your child may make a different decision the second time, especially after seeing how quickly small purchases use up the budget.
Try to keep the conversation about choices and consequences, rather than labelling purchases as good or bad. A snack can be a perfectly reasonable use of spending money. The skill is knowing what they can afford while still making progress towards something else they want.
If you’d like more activities beyond saving, explore these money games for kids to play at home.
How do you turn a saving game into a money saving plan for kids?
A game gives children a chance to practise. A money saving plan for kids puts that practice into a routine they can follow with their own money. Keep the plan short enough that your child can explain it back to you.
Choose one goal. Ask your child what they want to save for and check the price together. Let them have a say in the choice. They’re more likely to understand the purpose of saving if the goal matters to them.
Work out how long it will take. If the item costs $20 and your child can save $4 each week, they’ll need five weeks to reach the target, provided they save the full amount each week and have no existing savings. If that timeline feels too long, look at a cheaper option or agree to wait longer.
Decide what to set aside. Talk about how much of their pocket money can go towards the goal. A fixed amount may be easier for a younger child to follow than a percentage. Make sure they still have some money available to spend, if that’s part of your family’s pocket-money arrangement.
Track each contribution. Use a paper chart, checklist or savings jar. Check progress together once a week, rather than asking about it every day. If your child receives money at irregular times, update the tracker whenever they make a contribution.
Review the plan when things change. Perhaps your child spends some of their savings, or the item costs more than expected. Work out how much they still need and decide whether to adjust the amount or the deadline. There’s no need to treat a changed plan as a failure.
The aim is to help children see how their decisions affect their progress. They won’t always stick to the plan, and that’s part of learning to manage money.
Where can children practise money decisions before using real money?
Children can explore saving, spending and planning through games and simulations before applying those ideas to their own pocket money. MoneyKids Financial Literacy Bootcamp covers money-related topics through play-based learning, games and simulations, giving children a structured setting to explore financial decisions without needing to make real financial transactions during the activities.
This may suit parents who want their children to explore money concepts beyond the home. You can reinforce the learning with small decisions at home, such as comparing prices, talking through a purchase or checking how much remains before a savings goal is reached.
What if the kids keep spending their savings?
There ‘s always a chance when children may spend money they had planned to save, lose interest in a goal or discover something else they want more. Use it as an opportunity to review their plan and help them decide what to do next.
Break the goal into smaller milestones
A toy that costs $60 can feel out of reach if your child only receives a small amount of pocket money each week. Instead of focusing on the full price, divide the target into smaller amounts they can track.
If they save $5 each week, for example, reaching the first $15 gives them a milestone to work towards. They still need $45, but the goal may feel more manageable when they can see progress along the way.
For younger children, a visual tracker can help them follow that progress. Older children might prefer to record their contributions in a notebook.
If your child spends the money, talk about what happened
If they already spent the saved up money, it’s alright too.
Before telling them they should have saved the money, ask what led to the decision. Did they forget about the goal? Did the purchase seem more appealing at the time? Or had they never agreed on how much of their money was available to spend?
Their answers can help you work out what needs to change. You might need a clearer spending allowance, a more visible savings tracker or a goal that feels more meaningful to them.
They may need to save for longer as a result. Let them see that consequence without making them feel ashamed of the decision.
Adjust the timeline when needed
A savings plan should be realistic enough for children to follow. If the weekly contribution is too high, or your child has changed their mind about what they want, revisit the target.
You can work out a new timeline together or discuss a less expensive alternative. Avoid topping up the savings every time your child spends money they had planned to keep. If parents routinely replace the money, children may have less opportunity to understand how their own choices affect their progress.
Which saving activities work best for children aged 7–12?
The best activity depends on what your child is ready to practise.
Younger children may find it easier to work towards a visible target, while older children can take on more planning, such as calculating weekly savings or adjusting a budget when costs change.
These aren’t strict age rules. If your child already understands the basics, there’s little point in repeating them simply because an activity is labelled for their age group.
Choose the challenge that addresses what they struggle with, and make it harder as they become more confident.
Helping your child save money takes practice and patience, and they won’t always get it right the first time. Start easy with a goal they care about, let them make their own choices, and help them work through setbacks along the way. Over time, these small exercises can help them become more comfortable managing money and saving towards something they want.